Financial Planning for Physicians
A plan built for a late start, a high income, and very little spare time.
Schedule Your Consultation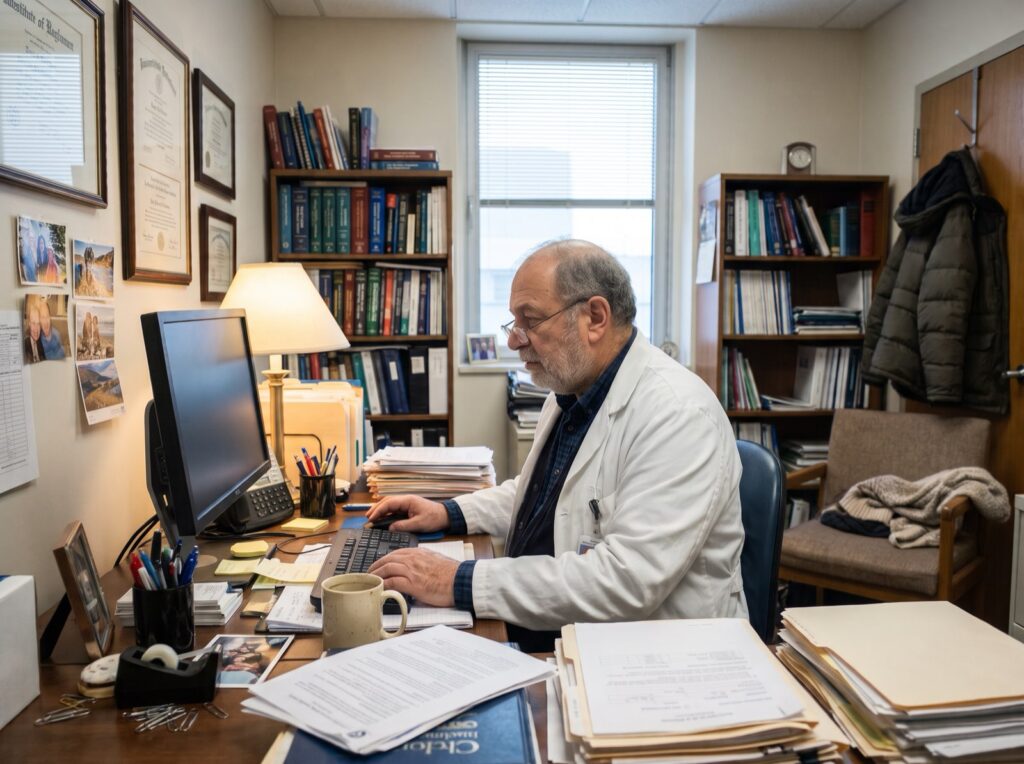
Medicine trains you to care for everyone else’s health. It rarely trains you to manage your own finances.
Most physicians begin earning a full income in their thirties, often after years of training and a significant student loan balance. Then the income arrives all at once, along with a long list of decisions: how to handle loans, which retirement plans to use, how to protect your ability to earn, and what to do about a tax bill that grows with every raise. Meanwhile, you have few hours left for personal finance.
That’s where we come in. Palm Capital Management is a fiduciary financial advisor in Calabasas, California, working with physicians, doctors, and surgeons in Calabasas, Agoura Hills, Westlake Village, and Woodland Hills; hospital systems and medical groups across the San Fernando and Conejo Valleys; and doctors nationwide. A physician’s financial life has a shorter runway to build wealth and more moving parts, and getting the early decisions right makes everything that follows easier.
Where We Start: Your Target Savings Rate
Rather than comparing you to peers who started saving a decade earlier, we start with where you are today. We calculate how much you need to save each year, based on your age, income, debts, and desired lifestyle, to reach the retirement you’re aiming for.
That number is more useful than a generic rule of thumb because it reflects your actual timeline. It also shows how much of the plan depends on your savings rate versus decisions about loans, taxes, and career moves.
Same retirement age, a much later start
A typical career
Saving can start with the first paycheckA steady rate, with decades to compound
A physician’s career
Medical school + residencyOften 7–11 years: loans, little saving
Income steps upRepay loans and save at a higher rate to catch up
What We Help Physicians Think Through
Physician student loan strategy.
Whether to refinance, pursue a federal forgiveness program such as Public Service Loan Forgiveness, or pay loans down aggressively depends on your loan type, your employer, and your income. We compare options with your numbers rather than a rule of thumb.
Disability and life insurance for physicians.
Your ability to practice your specialty is your largest financial asset. As part of our risk management work, we review disability insurance, including how the policy defines disability and whether it’s portable if you change jobs, along with your family’s life insurance needs.
Tax-efficient retirement planning for doctors.
Depending on your employment setup, that can mean maximizing a 401(k) or 403(b), using a 457(b) if you have one, and funding Roth accounts through strategies built for high earners. For practice owners and partners, we also look at whether a cash balance plan makes sense. With California income tax on top of federal, tax-efficient saving matters even more.
Contracts, partnerships, and practice transitions.
Employed or partner, a practice buy-in, a new contract, locum work, or a sale of your share of the practice. We help you understand how each change affects your finances, working alongside your attorney and CPA.
Liability and asset protection.
Malpractice coverage, umbrella liability insurance, and how you title and hold your accounts can affect your asset exposure. We coordinate with your attorney, since protections vary by state.
Big goals and planning your exit.
Buying a home in Southern California on a physician’s timeline, funding your children’s education, and deciding when you can realistically slow down or stop. We stress-test the plan against a market downturn, a health event, or a longer-than-average lifespan.
Our Approach
Palm Capital Management uses fundamental analysis and a long-term, tactical approach to build portfolios around your goals, not the other way around. As fiduciaries, we’re legally obligated to act in your best interest, and we keep our own investable assets alongside our clients’, so our incentives stay aligned with yours.
We also believe cost matters. Hidden fees in mutual funds and other structured products can quietly erode a portfolio over time, so we favor low-cost, transparent holdings that give you direct ownership and more control. For a busy physician, that also means a portfolio you can understand without spending your evenings on it.
Portfolios built around your goals
Fiduciary, invested alongside you
Low-cost, transparent holdings
Common questions
Physician Financial Planning FAQs
Straight answers to the questions we hear most from physicians at every stage of their careers.
Got more questions?
Ask us anythingShould I pay off student loans or invest first?
It usually isn’t either/or. The answer depends on your loans’ interest rates, whether you’re eligible for forgiveness, and whether your employer offers a retirement match you’d otherwise leave on the table. We run the numbers for your situation.
Do I need my own disability insurance if my employer provides it?
Often, yes. Group coverage can define disability narrowly, cap benefits below your income, and generally end when you leave your job. An individual policy can fill those gaps, and we help you compare the definitions that matter most.
What is a backdoor Roth, and does it apply to me?
It’s a strategy that lets high earners above the Roth IRA income limits still fund a Roth account. It works well for many physicians, but existing pre-tax IRA balances can change the tax result, so it’s worth checking before you start.
Is a cash balance plan right for me?
It can be, mainly for practice owners and partners with high, stable income who want to save well beyond standard retirement plan limits. It comes with funding commitments, so it’s a decision to make with your CPA and plan administrator.
I’m still a resident or fellow. Is it too early to work with a financial advisor?
No. Loan choices, disability coverage, and early savings habits often matter most at this stage, and a plan in place before your first attending salary helps you avoid the common traps.
Do you work with physicians outside Calabasas?
Yes. Our office is on Calabasas Road in Calabasas, California, and we meet with clients in person or by video. We work with physicians across the country.
Words from Our Clients
Independent Google reviews from those who trust us with their financial future.
“Alano has been managing my now quite sizeable Schwab rollover IRA and revocable trust accounts for 11 years. I’ve left practically all investment choices to him. The funds have grown substantially under his guidance. He and his staff have always been available and responsive to any requests I have for documents or explanations.”
— Donald S.
This is an unpaid solicited client testimonial. The client has had a financial relationship with Alano Massi for over 10 years and is providing his opinion. A client testimonial does not guarantee future investment success and should not be that any client or prospective client will experience a higher level of investment performance. This may present a conflict of interest as this particular client’s experience may or may not be the same as another client’s experience.
“I have worked with Alano Massi for several years and it has been an exceptional experience. Alano is very professional and knowledgeable, and he always makes time to understand my specific goals. Alano and his staff provide prompt and friendly communication, always available to answer my questions and ease my concerns.”
— Sarah C.
This is an unpaid solicited client testimonial. The client has had a financial relationship with Alano Massi for over 7 years and is providing her opinion. A client testimonial does not guarantee future investment success and should not be that any client or prospective client will experience a higher level of investment performance. This may present a conflict of interest as this particular client’s experience may or may not be the same as another client’s experience.
Financial Resources for Physicians
You May Also Be Interested In
Ready to Turn Your Income Into a Plan?
Schedule a complimentary consultation with our Calabasas financial planning team and let’s build the plan that puts your hard-earned income to work.